15, 20 or 25 Years? How Loan Tenure Changes Your EMI and Total Interest
Compare 15-, 20- and 25-year loan tenures to see how the monthly EMI, total interest and budget flexibility can change.
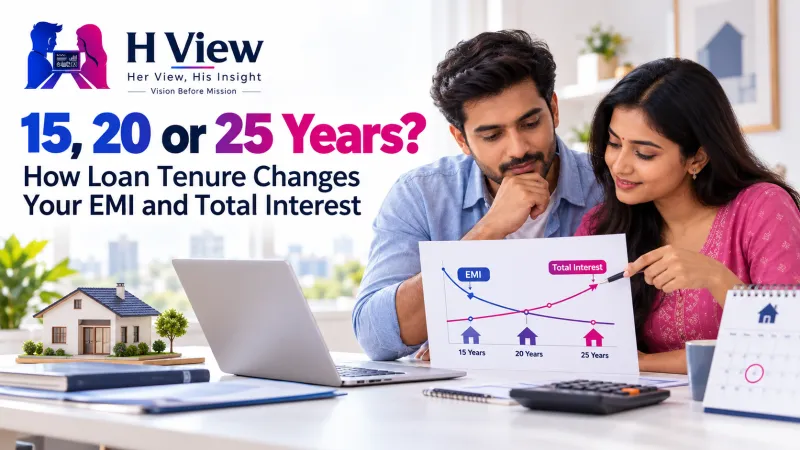
For the same loan amount and interest rate, a longer repayment tenure generally lowers the monthly EMI but increases the total interest paid if the loan runs to term. A shorter tenure usually raises the EMI while reducing total interest. The right tenure is the one that balances affordability, flexibility and the cost of borrowing for your household.
How much can tenure change the cost?
Illustration: a ₹50 lakh loan at a constant 8.5% annual interest rate, repaid monthly, with no fees or rate changes. Approximate figures:
| Tenure | Approx. EMI | Approx. total interest |
|---|---|---|
| 15 years | ₹49,237 | ₹38.6 lakh |
| 20 years | ₹43,391 | ₹54.1 lakh |
| 25 years | ₹40,261 | ₹70.8 lakh |
This is a mathematical illustration using a fixed rate and standard reducing-balance EMI formula. A lender’s actual schedule can differ because rates may reset, disbursement can be staged and fees or insurance may apply. The table shows the trade-off: moving from 15 to 25 years reduces the illustrative EMI by about ₹8,976 per month but adds roughly ₹32.2 lakh in interest if all other assumptions hold.
How should you choose a repayment tenure?
- Start with a monthly EMI that remains manageable after essential expenses and savings.
- Stress-test the budget for a rate increase, income interruption or new family expense.
- Compare total interest and lender charges, not only the EMI shown in an offer.
- Ask whether part-prepayment is allowed and how it changes the schedule.
- Keep enough liquidity for emergencies rather than using every rupee to shorten the loan.
The RBI home-loan FAQ is a useful source for general borrower questions. Lenders should provide the applicable loan terms and repayment schedule; review the sanction letter and current rate-reset policy. H View’s EMI calculator can model different tenures using your own loan amount and rate.
 Also readHome Loan Prepayment: How Extra Payments Can Reduce Interest→
Is the lowest EMI always the best choice?
No. A low EMI can make a loan easier to manage month to month, but a longer term may keep you in debt for longer and cost more in interest. Conversely, an aggressive EMI can leave too little room for savings or unexpected costs. Choose based on a realistic cash-flow plan, then review it when your income or rate changes.
Frequently asked questions
Can I choose a longer tenure and prepay later?
That may preserve monthly flexibility, but prepayment rights and charges depend on your loan terms and applicable RBI rules. Confirm both before signing.
Why does the interest total rise so sharply over longer terms?
The outstanding balance is repaid more slowly, so interest can accrue for more months. The exact result depends on the rate and payment schedule.
Are these EMI figures a lender quote?
No. They are estimates under stated assumptions. Ask the lender for its amortisation schedule, fees and reset scenarios.
This guide is general information, not financial advice. Loan offers and regulatory terms vary; verify the figures and conditions with your lender.
H View stories follow our editorial policy. Spotted an error? Tell us and we will correct it.
Rate this article
One tap is enough. No comment needed.
Was this article helpful?
Your answer goes straight to our editors.
Comments0
No comments yet. Start the conversation.