Home Loan Prepayment: How Extra Payments Can Reduce Interest
See how a home-loan part-prepayment affects principal, EMI and tenure, with a practical checklist for comparing lender options before paying extra.
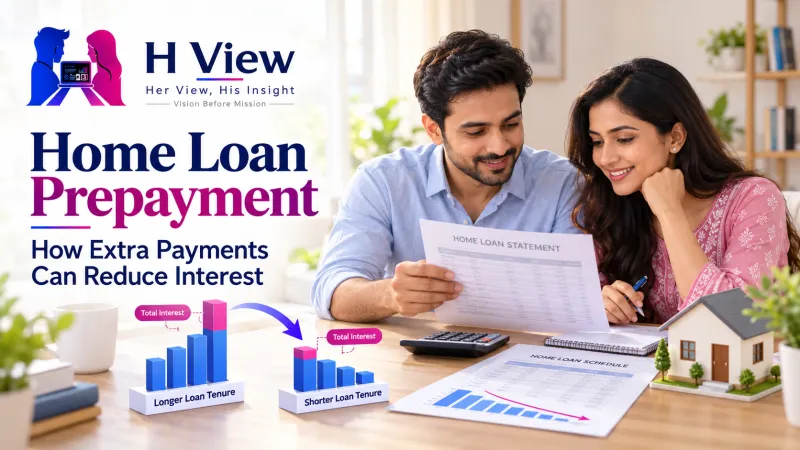
A home-loan part-prepayment reduces the principal on which future interest is calculated. If your lender applies the extra payment directly to principal, you can usually choose to keep your EMI and shorten the loan, or reduce the EMI and retain the original tenure. The better option depends on your cash reserves, loan terms and goals.
How does a part-prepayment change a home loan?
Home-loan EMIs include interest and principal. Early in a long loan, a larger share of each EMI generally goes toward interest. A lump-sum payment can lower the outstanding principal, so future interest is calculated on a smaller balance. The effect depends on the rate, remaining tenure, timing and lender’s method.
For illustration, consider a ₹30 lakh balance at 8.5% with 15 years remaining. A ₹2 lakh part-payment could bring the balance near ₹28 lakh before future EMI processing. This is not a guaranteed savings figure: the actual interest saved depends on when the payment posts, the lender’s rules and whether you reduce the EMI or tenure. Use a loan calculator with your current statement figures before deciding.
Should you reduce the EMI or shorten the tenure?
| Choice | What changes | May suit you when |
|---|---|---|
| Keep EMI, shorten tenure | Monthly payment stays similar; loan may end sooner | You can comfortably afford the current EMI and want to reduce total interest |
| Reduce EMI, keep tenure | Monthly outflow falls; loan end date stays similar | You need more room in your monthly budget |
Ask your lender to show both revised schedules in writing. Confirm that the payment is treated as principal prepayment rather than an advance EMI, and check for any minimum amount, payment window or processing steps.
 Also readFake Instant Loan Apps in India: How “Loan Approved in 5 Minutes” Can Turn Into a Financial Nightmare→
What should you check before paying extra?
- Keep an emergency fund for essential expenses and near-term needs.
- Compare the loan’s effective interest cost with other expensive debt you could repay.
- Check your sanction letter and lender’s current prepayment terms.
- Ask whether your rate is fixed or floating and what rules apply to your loan type.
- Save the receipt and verify the principal balance after the payment posts.
The Reserve Bank of India’s 2025 directions on pre-payment charges set rules for covered loans and lenders. Applicability depends on the loan, borrower and sanction or renewal date; read the official directions and your lender’s terms. The RBI home-loan FAQ is a useful starting point for general loan questions.
Frequently asked questions
Can I prepay a home loan in small amounts?
Many lenders allow part-payments, but minimum amounts and channels vary. Confirm the process with your lender before transferring money.
Is reducing tenure always better?
No. It can reduce interest when you can sustain the EMI, but lowering the EMI may be more practical if your budget is tight or income is uncertain.
Where can I compare EMI choices?
Use H View’s EMI calculator to model monthly payments, then ask your lender for an updated amortisation schedule. Treat any online estimate as illustrative.
This guide is general information, not financial advice. Loan terms and regulatory applicability can vary; verify details with your lender and RBI.
H View stories follow our editorial policy. Spotted an error? Tell us and we will correct it.
Rate this article
One tap is enough. No comment needed.
Was this article helpful?
Your answer goes straight to our editors.
Comments0
No comments yet. Start the conversation.