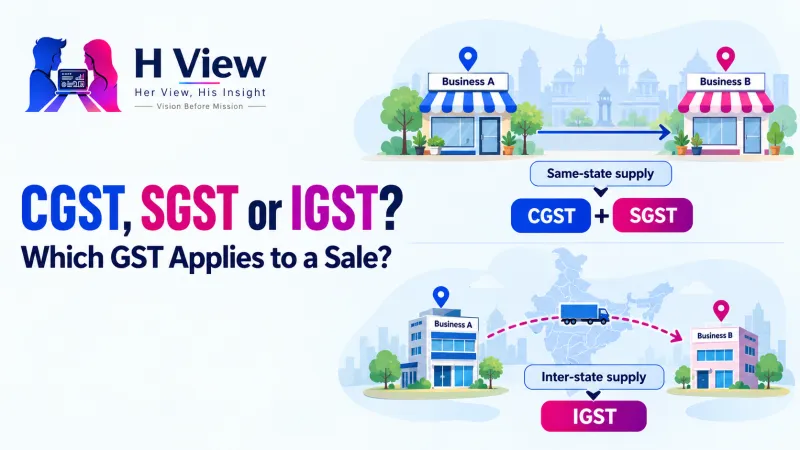
CGST, SGST or IGST? Which GST Applies to a Sale?
A simple guide to when a GST invoice generally uses CGST with SGST or UTGST, and when IGST may apply under India’s place-of-supply rules.
For many GST transactions within one State or Union Territory, the invoice shows CGST plus SGST or UTGST. For an inter-State supply, IGST is generally charged. The correct tax depends on the legal place-of-supply rules and the supplier’s location, so a billing address or delivery address alone may not answer every case.
What is the practical difference between CGST, SGST and IGST?
| Tax | Common use | How it appears |
|---|---|---|
| CGST | Central component of a typical intra-State taxable supply | Charged alongside SGST or UTGST |
| SGST | State component of a typical intra-State supply | Charged with CGST for the relevant State |
| UTGST | Union Territory component in applicable intra-UT supplies | Charged with CGST where UTGST applies |
| IGST | Generally, an inter-State taxable supply and specified cross-border cases | One integrated tax line, subject to the governing provisions |
How do you decide which tax to show?
First identify the supplier’s location. Next classify the supply and determine its place of supply under the GST law. If the supplier location and place of supply are in the same State/UT, a typical intra-State sale uses CGST with SGST/UTGST. If they are in different States/UTs, a typical inter-State sale uses IGST. Special rules apply to services, goods involving movement, exports, imports and other cases.
Example: a seller located in Maharashtra supplies goods for delivery within Maharashtra. If the statutory place of supply is Maharashtra, the transaction is generally intra-State. If a supplier in Maharashtra makes a taxable supply whose place of supply is Karnataka, it is generally inter-State. These examples are simplified; apply the relevant place-of-supply provision to the actual contract and movement.
 Also readGST Invoice Format in India: Essential Fields and a Practical Checklist→
What details should you check before invoicing?
- Supplier registration and location on the date of supply.
- Recipient registration status and the recipient’s location.
- Nature of supply: goods, services, export, import or another category.
- Applicable place-of-supply rule, including any special rule.
- Tax rate and whether the invoice should split CGST/SGST or show IGST.
CBIC’s GST overview explains the dual GST structure. Read the relevant CBIC GST rate information and legislation for current rates and conditions. H View’s GST calculator can calculate a stated rate on a price, but it cannot determine your place of supply or select the legally correct rate.
Frequently asked questions
Do I charge both CGST and IGST?
For the same ordinary taxable supply, the tax treatment is generally either CGST with SGST/UTGST or IGST, based on the applicable rules. Check special cases before issuing an invoice.
Is an out-of-State billing address enough to decide?
No. Determine place of supply using the applicable statutory rule and facts of the transaction.
Can an online calculator choose the correct GST tax?
A calculator can do arithmetic once you know the applicable tax rate. It cannot replace a tax classification or place-of-supply analysis.
This guide is general information, not tax or legal advice. Confirm classification, place of supply and rates using current CBIC guidance or a GST professional.
H View stories follow our editorial policy. Spotted an error? Tell us and we will correct it.
Rate this article
One tap is enough. No comment needed.
Was this article helpful?
Your answer goes straight to our editors.
Comments0
No comments yet. Start the conversation.