
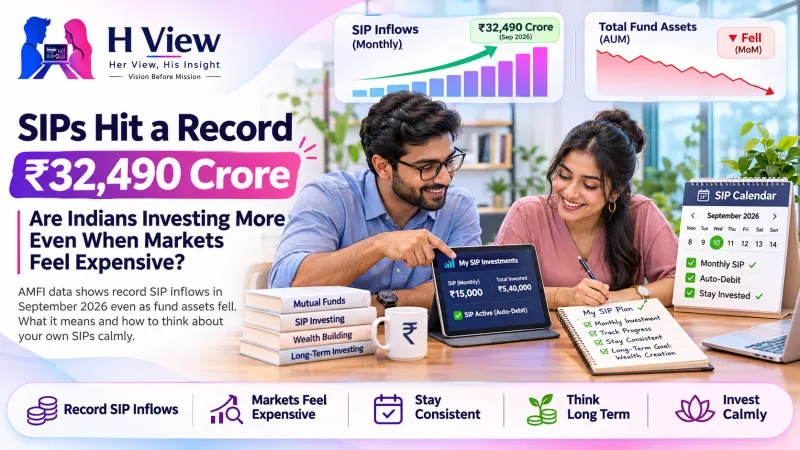
SIPs Hit a Record ₹32,490 Crore—Are Indians Investing More Even When Markets Feel Expensive?
Record SIP money, falling fund assets and nervous headlines. Here is what September's AMFI data really says, and what it does and doesn't mean for your own SIP.
Short answer: Yes. SIP inflows reached a record ₹32,490 crore in September 2026, according to AMFI data, even though total mutual fund assets fell 5.1% that month. Millions of Indians kept investing on autopilot through a weak market. That habit is useful, but a record number is not a reason to invest more than your plan allows.
Last reviewed: 3 November 2026. This article is general information, not personal financial advice.
Every month there is a new headline: "SIPs at an all-time high." And every month a friend asks the same thing over chai: are people being brave, or are they being foolish? September 2026 gives us an interesting answer, because the record came in a month when markets were anything but cheerful.
What the September 2026 numbers say
| Metric (AMFI) | September 2026 | Comparison |
|---|---|---|
| Monthly SIP contributions | ₹32,490 crore (record) | ₹32,297 crore in August; ₹29,361 crore in September 2025 |
| Net inflows into equity funds | About ₹38,307 crore | Up roughly 31% from August |
| Total mutual fund assets (AUM) | ₹82.64 lakh crore | Down 5.1% from ₹87.08 lakh crore |
| Debt fund flows | Net outflow of about ₹1.83 lakh crore | A big reason total assets fell |
So money kept coming in through SIPs, equity funds attracted even more, yet the total value of the industry shrank. That is not a contradiction. Assets fall when market prices drop and when large investors, often companies parking short-term cash, pull money out of debt funds. Your monthly ₹5,000 SIP and a corporate treasury's quarter-end withdrawal are very different things.
Why are people still investing when markets feel expensive?
Automation removes the daily decision
An SIP is an instruction to invest a fixed amount every month. Once it is set up, you don't have to decide each month whether the market "feels right". About 10 crore SIP accounts contributed in September, and most of those investors did nothing more than let the auto-debit go through.
Rupee cost averaging feels reassuring in a dip
When prices fall, the same SIP amount buys more units. Many investors have learnt from earlier cycles that continuing through a dip can lower their average cost over time. It doesn't guarantee profits, but it removes the pressure to time the market.
Goals don't pause for headlines
A child's education, a home down payment or retirement are years away. People investing for those goals tend to keep going regardless of one bad month, and that discipline shows up in the data.
 Also readGold vs Silver vs Fixed Deposits: How Should Families Compare Their Savings Options?→
What the record does not mean
- It doesn't mean markets will rise next. Inflows show behaviour, not future returns.
- It doesn't mean everyone is doing well. Small-cap funds led inflows in September. Those funds can swing sharply, so investors chasing recent winners carry more risk than they may realise.
- It doesn't mean you should increase your SIP because others are. The right amount depends on your income, emergency fund and goals, not on a national total.
A calm checklist for your own SIPs
- Emergency fund first. Keep three to six months of expenses somewhere safe and easy to reach before stretching your SIPs.
- Match the fund to the goal. Equity funds suit long goals of five years or more; money needed in a year or two usually belongs somewhere less volatile.
- Check overlap. Four funds holding the same large companies is not real diversification.
- Review once or twice a year, not every time the market moves.
- Step up with your salary. Increasing your SIP when your income rises is often more powerful than reacting to headlines.
If festive spending has stretched your budget, it is better to pause or reduce an SIP for a month than to skip loan EMIs or rely on a credit card. Gold is the other big festive-season choice; our comparison of gold, silver and fixed deposits may help you weigh it.
Her View
In many families, SIPs were started by one person and the rest of the household doesn't know what they are or where they sit. A record month is a good excuse to sit together, list every SIP, its goal and its nominee. Financial confidence grows when knowledge is shared, not when one person carries it all.
 Also readIPO Allotment Status: How to Check Your Application Safely→
His Insight
The interesting signal isn't the record itself, it's that inflows rose in a falling month. That suggests Indian retail investors are becoming steadier. The risk is complacency: steady habits work best when they are paired with sensible fund choices and an honest look at how much volatility you can live with.
Related reading: what makes up your salary, new vs old tax regime and what counts as taxable income.
Frequently asked questions
What were SIP inflows in September 2026?
According to AMFI data released on 12 October 2026, monthly SIP contributions were a record ₹32,490 crore, up from ₹32,297 crore in August.
Why did mutual fund AUM fall if SIPs rose?
Total assets fell mainly because of large outflows from debt funds and lower market prices. SIP money is only one part of the total.
Should I stop my SIP when markets fall?
Stopping in a dip means buying fewer units when prices are lower. If your goal and ability to invest haven't changed, many investors continue. If your finances have changed, reduce or pause rather than borrow.
Is a bigger SIP always better?
No. Invest an amount you can sustain for years without dipping into your emergency fund. Consistency usually matters more than size.
Sources
H View stories follow our editorial policy. Spotted an error? Tell us and we will correct it.
Rate this article
One tap is enough. No comment needed.
Was this article helpful?
Your answer goes straight to our editors.
Comments0
No comments yet. Start the conversation.