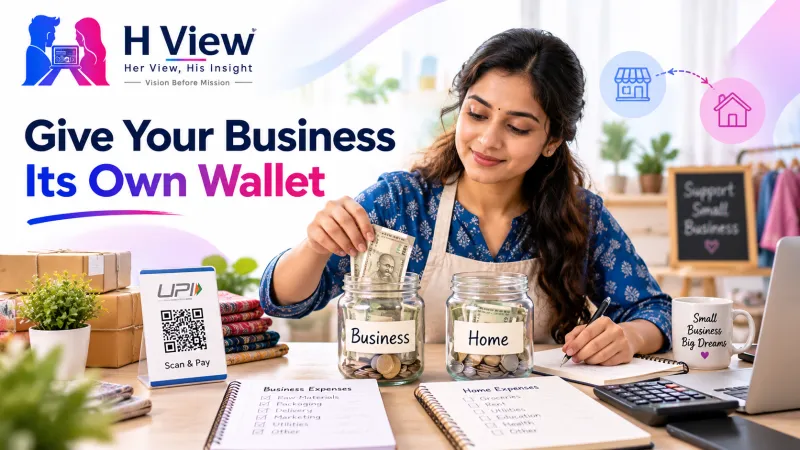
Business Money or Household Money? A Simple System for Women-Led Small Businesses to Keep Them Separate
When business earnings go straight into the kitchen budget, no one knows whether the business is actually making money. A simple, practical system to separate business and household money.
A woman runs a small catering business from home. Customers pay through UPI to her personal account. The same account pays for groceries, school fees, gas cylinders and family emergencies. When someone asks whether the business is profitable, she honestly does not know. Some months feel good, others feel tight, and the money seems to disappear.
This is one of the most common problems in women-led small businesses. When business and household money are mixed, the business becomes invisible: its profit, its costs and its growth all disappear into the family budget.
Learning to separate business and household money is not about complicated accounting. It is a few simple habits that make your business visible to you, your family and your bank.
Why Mixing Money Hurts the Business
You can’t see your real profit
If business payments and household expenses share one account, there is no way to know whether the business earned ₹5,000 or ₹25,000 this month.
The business quietly funds the house
Business earnings often get used for immediate family needs. Then, when it is time to buy raw material for the next order, there is no money left, and the business borrows from the household or from moneylenders.
Banks see no business history
When you apply for a loan, banks look at your transactions. If all business income looks like personal transfers mixed with household spending, it is difficult to show a stable business record.
Family conflict increases
When money is mixed, family members may see the business as “extra cash” rather than a working enterprise that needs reinvestment. That can create tension, much like the money fights we discussed in why couples fight about money.
A Simple Five-Step System
Step 1: Open a separate account for the business
This can be a separate savings account used only for business, or a current account in the business name if your bank supports it. Ask your bank which option suits a small business. If you have Udyam registration, keep a copy ready; it can help when opening business accounts.
Step 2: Receive all business payments only into that account
Use a UPI ID or QR code linked to the business account, and share only that with customers. Avoid letting customers pay into family members’ accounts.
Step 3: Pay all business expenses only from that account
Raw material, packaging, delivery charges and equipment should be paid from the business account. If you must pay from personal money in an emergency, note it and repay yourself from the business account later.
Step 4: Pay yourself a fixed “salary”
Once a month, transfer a fixed amount from the business account to your personal or household account. This is your income from the business. What remains in the business account is for running and growing the business.
Step 5: Keep a simple record every week
A notebook or a free spreadsheet is enough. Note:
- Date, customer and amount received.
- Date, supplier and amount spent.
- Monthly total income, total expenses and what you paid yourself.
Spending fifteen minutes on this every Sunday will tell you more about your business than months of guessing.
 Also readWhy Women Running Home Businesses Undercharge—and How to Price Your Work Properly→
A Quick Monthly Snapshot
| Item | Example amount |
|---|---|
| Total business income | ₹42,000 |
| Business expenses | ₹21,000 |
| Your monthly “salary” to household | ₹12,000 |
| Left in business for growth and emergencies | ₹9,000 |
These figures are only an example. The point is that every rupee has a clear place, and you can see whether the business is growing.
What This Changes
- You know your real profit and which products actually earn money.
- You price better, using real costs. See our guide on how to price your home business.
- You build a transaction history that banks can understand.
- Your family sees a regular income from your work, not random cash.
Her View: Your Business Deserves Its Own Wallet
Women are often the ones who hold the household together financially, stretching every rupee. So when business money comes in, it naturally flows to whatever the family needs first. That instinct comes from care, but it slowly starves the business.
Giving your business its own account is a way of saying: this work matters, it needs to survive, and it deserves to grow. It also protects you, because your contribution to the household becomes visible as a regular salary, not as invisible support. This visibility gap is a big reason many enterprises struggle to grow after SHGs.
 Also readUdyam Registration for Women Entrepreneurs: Why a Free Certificate Can Change How Your Business Is Treated→
His Insight: Separation Is the First Step to Scale
Every growing business, small or large, keeps business and personal finances separate. It is how owners measure performance, plan purchases and handle tax and compliance as they grow.
Starting this habit while the business is small is far easier than untangling years of mixed transactions later. It also makes conversations about loans, partnerships or larger buyers much simpler.
H View Verdict
Mixing business and household money hides profit, drains working capital and weakens your case with banks. A separate account, payments only through business channels, a fixed monthly salary for yourself and a weekly record are enough to change that.
It takes a little discipline at first. But once business money has its own home, you will finally see what your hard work is really earning, and so will everyone else.
Frequently Asked Questions
Do I need a current account for a small home business?
Not always. A separate savings account used only for business can work at the start. Ask your bank whether a current account in the business name is better for your situation.
How much should I pay myself from my business?
Choose a fixed amount the business can afford after expenses, and leave the rest for raw material, growth and emergencies. Adjust it as the business grows.
What is the easiest way to keep business records?
A simple notebook or free spreadsheet listing income, expenses and your monthly salary, updated once a week, is enough for most small businesses.
Why do banks care about separate business accounts?
A separate account shows a clear record of business income and expenses, which helps banks understand your repayment capacity.
H View stories follow our editorial policy. Spotted an error? Tell us and we will correct it.
Rate this article
One tap is enough. No comment needed.
Was this article helpful?
Your answer goes straight to our editors.
Comments0
No comments yet. Start the conversation.