Best Digital Marketing Tools in 2026: What Marketers Actually Need and What They Can Skip
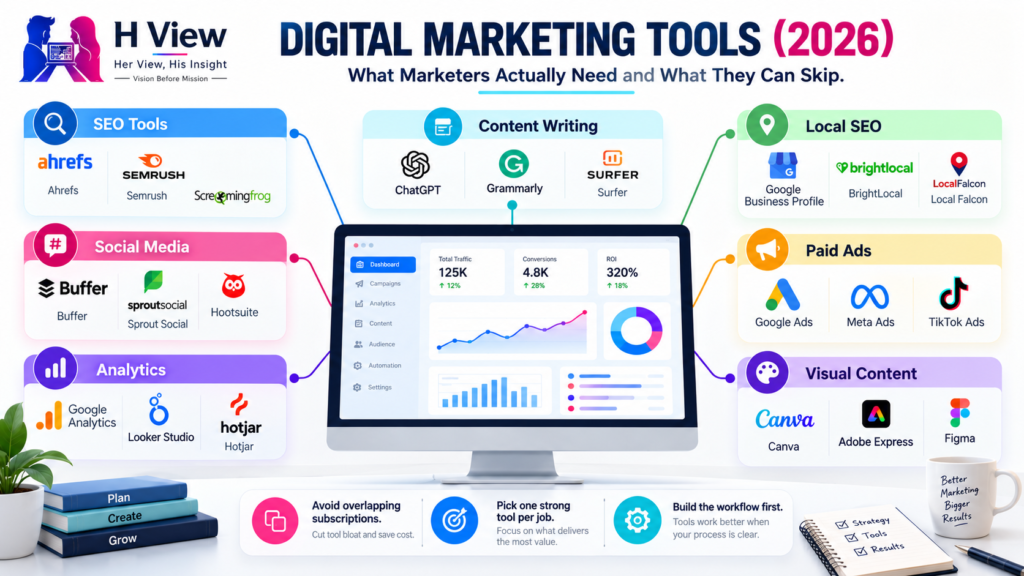
Open LinkedIn for a few minutes and you will probably come across a colourful graphic…
 Harika October 6, 2026
 By AnnapurnaUpdated September 28, 202614 min read12 views
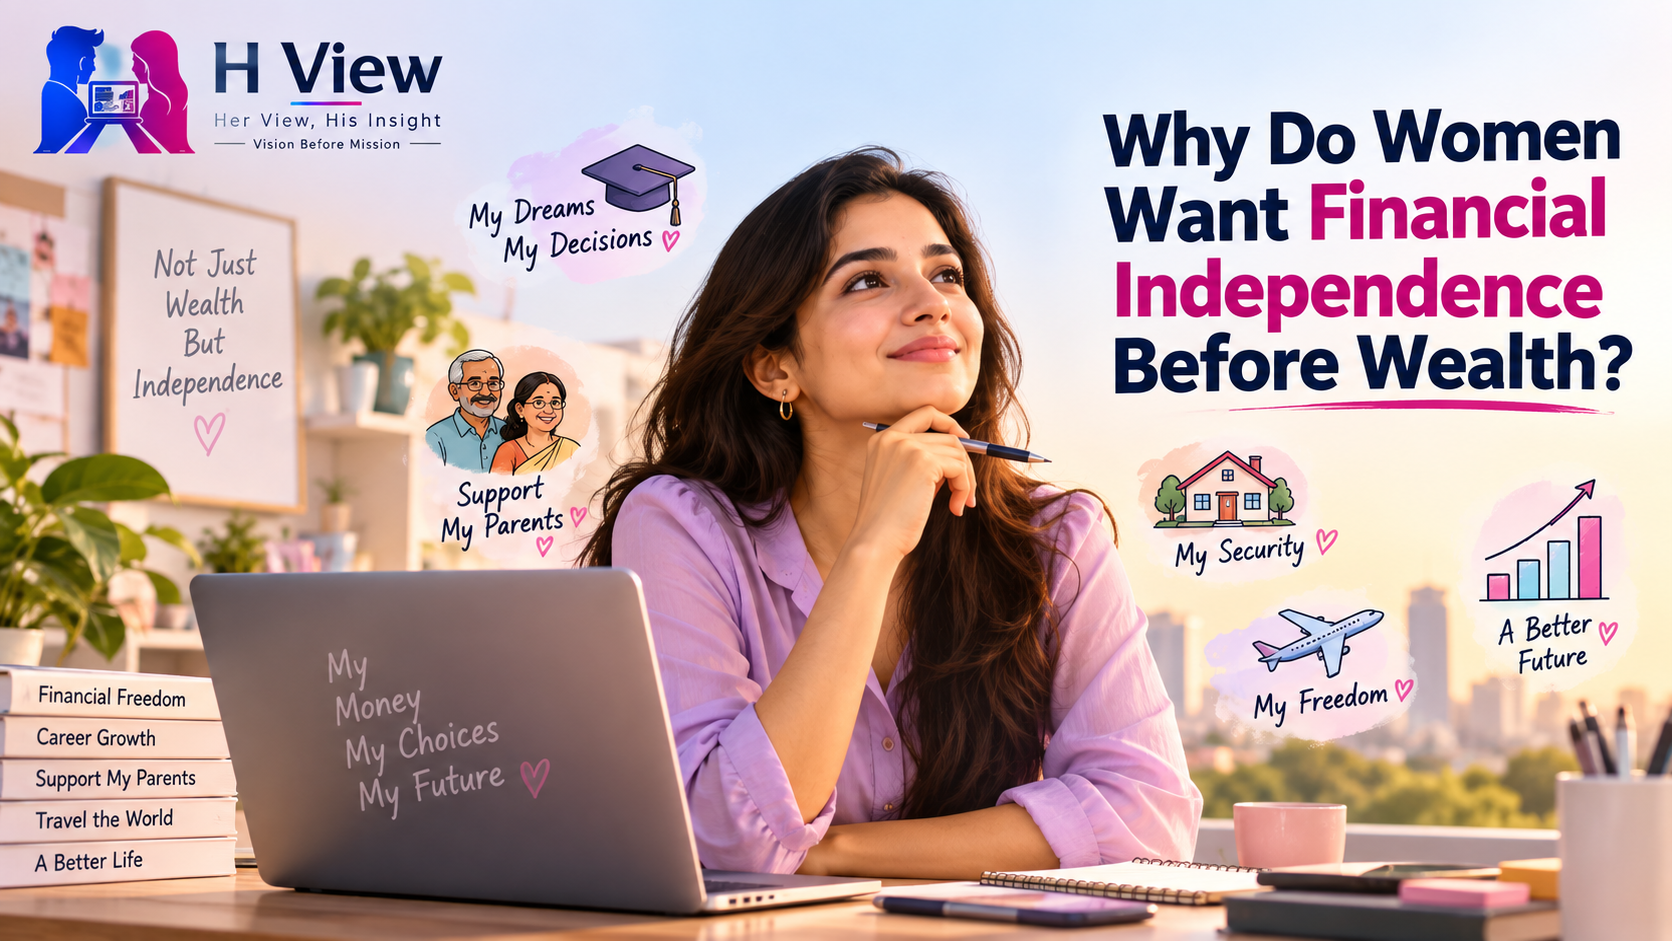
When people hear that a young woman wants to earn well, save aggressively, or become financially independent before marriage, the conversation can quickly turn toward ambition, lifestyle, or wealth. It may be assumed that she wants expensive things, a luxurious life, or the freedom to spend without accountability. For many women, however, the motivation is considerably more ordinary and considerably more important: they want to reach a stage where everyday choices do not require financial dependence on another person.
Financial independence can mean being able to pay for a medical emergency without wondering whom to ask, buy something necessary without explaining every expense, support ageing parents from her own income, leave an unhealthy situation if life demands it, take a career break without immediately losing economic security, or simply know that her future does not depend entirely on somebody else’s decisions. Wealth may eventually create comfort, but financial independence creates something more fundamental first: choice.
This distinction is increasingly visible in India. More than 59 crore accounts had been opened under the Pradhan Mantri Jan-Dhan Yojana by August 2026, and women accounted for 56% of them. Having a bank account does not automatically create financial independence, but access to formal banking is an important first step toward having money, savings, credit, insurance, and financial decisions connected directly to a woman’s own name.
A woman earning ₹35,000 a month and consistently saving part of it may have more practical financial independence than someone living in a wealthy household with no access to money of her own. Wealth describes the quantity of financial resources available, whereas financial independence is also about control, accessibility, knowledge, and the ability to make reasonable decisions without repeatedly seeking permission.
This is why the aspiration should not be misunderstood as a race to become rich. Many women are not dreaming first about luxury cars, designer products, or enormous investment portfolios. They are trying to build enough security to ensure that ordinary life choices remain possible even when circumstances change.
The difference becomes clearer when we compare the two ideas.
| Financial independence | Wealth |
|---|---|
| Having accessible savings in your own control | Accumulating substantial assets |
| Being able to handle personal emergencies | Being able to afford a higher standard of living |
| Understanding and participating in financial decisions | Building large investments and long-term capital |
| Having the ability to support yourself when necessary | Having significant surplus resources |
| Maintaining some financial choice within relationships | Expanding financial opportunities and lifestyle choices |
| Creating a basic safety net | Creating intergenerational or long-term wealth |
Ideally, women should have opportunities to build both. However, independence usually needs to come first because wealth has limited protective value if a woman cannot access, understand, or make decisions about the money around her.
Financial dependence is often discussed through extreme situations, but its effects can appear in very small moments. A woman may hesitate before buying something for herself because she has to justify the expense, delay visiting a doctor because she does not want to ask for money, or feel uncomfortable contributing to a friend’s celebration because she does not personally control household finances.
None of these examples necessarily indicates an abusive or unhappy family. Couples naturally discuss major spending, and responsible financial planning requires accountability from both partners. The concern begins when one adult has meaningful financial authority while the other has to seek approval for ordinary personal needs.
That is why earning can carry emotional significance beyond the amount printed on a salary slip. The first salary may represent the first time a woman can make a small financial decision entirely on her own, and that experience can change how she sees herself.
One of the least discussed reasons women value financial independence is the desire to support their own parents. Sons have traditionally been expected to provide financial assistance to ageing parents, while married daughters may sometimes feel that contributing to their parents requires discussion or permission because their income is now considered part of their marital household.
For a woman who watched her parents invest years of savings, effort, education, and care into her future, this can be emotionally difficult. She may not want to become her parents’ primary financial provider, but she may want the freedom to pay for a medical test, buy them something useful, contribute during an emergency, or simply give them money without feeling that she is redirecting somebody else’s resources.
Financial independence makes that contribution possible without turning affection into negotiation. It also recognises a changing reality in which daughters increasingly share responsibility for ageing parents rather than assuming that care automatically belongs to sons.
Employment alone does not guarantee financial independence. A woman can receive a salary every month while remaining disconnected from investments, insurance, taxation, retirement planning, loans, or even major financial decisions within her own household.
This is one reason the conversation needs to move beyond encouraging women merely to “earn.” Real financial agency involves knowing where money is kept, understanding how household finances work, building assets in one’s own name, participating in investment decisions, and having direct access to emergency funds.
Recent investment trends suggest that this change is beginning. AMFI and CRISIL data show that women’s SIP assets increased from about ₹1.21 lakh crore in December 2020 to ₹5.26 lakh crore in December 2025, more than quadrupling in five years. Separate 2026 research found that nearly 80% of women mutual-fund investors began investing before age 35, with SIPs playing a major role among younger investors.
Yet participation remains far from equal. Another 2026 study reported that women represented only about 26% of India’s unique mutual-fund investors, demonstrating that growing interest has not completely closed the investment gap.
A request for personal financial security should not automatically be interpreted as mistrust between spouses. Healthy marriages can have joint accounts, common investments, shared goals, and transparent financial planning while still ensuring that both partners retain some individual financial agency.
Life is unpredictable even in loving relationships. A spouse may lose a job, become seriously ill, die unexpectedly, experience business failure, or face circumstances that temporarily reduce household income. Women may also experience career breaks related to pregnancy, childcare, caregiving, or relocation, making personal savings especially important during periods when their own earnings decline.
A sensible financial structure can therefore combine shared and individual security rather than forcing couples to choose between them.
A woman may reasonably aim to have:
These are not preparations for marital failure. They are the ordinary foundations of adult financial responsibility.
Money does not solve every relationship problem, but financial dependence can make difficult relationships harder to navigate. A woman who has no independent savings, income, assets, or knowledge of household finances may have fewer practical options when facing controlling behaviour, separation, widowhood, family conflict, or an urgent need to relocate.
Research using Indian household data has linked women’s ownership of bank accounts with stronger bargaining power and greater participation in household decision-making. Financial inclusion alone cannot eliminate social inequality, but access to financial resources can affect how much influence a woman has over decisions concerning her own life.
This is one of the strongest reasons financial independence should not be portrayed as rebellion against family. A relationship becomes healthier when two adults remain together because they value the partnership rather than because one person cannot economically imagine life outside it.
Women’s earnings often do not follow a perfectly uninterrupted line from their early twenties to retirement. Pregnancy, childcare, elder care, relocation after marriage, family responsibilities, health, or a spouse’s transfer can interrupt employment and reduce both current income and long-term wealth accumulation.
The visible loss during a career break is salary, but the invisible losses can include promotions, increments, employer retirement contributions, professional networks, and years of compounding on investments. Financial planning before such a break can therefore provide far more than immediate spending money.
Recent Indian financial advisers have increasingly discussed maternity funds, sabbatical funds, emergency reserves, insurance, retirement investments, and personal investment portfolios as part of women’s financial planning. The broader trend reflects an important change: women are beginning to plan not only for family milestones but also for their own career transitions, homes, businesses, retirement, travel, and personal security.
Work does more than generate income. For many women it provides professional identity, confidence, social interaction, learning, problem-solving, and the satisfaction of knowing that their abilities have economic value.
That does not make homemaking less meaningful. A woman who chooses full-time caregiving or household management contributes substantial economic and social value even when that contribution does not arrive as a monthly salary. The real issue is whether she also has meaningful participation in financial decisions and adequate financial protection for the work she performs.
A homemaker should not have to become invisible in the family’s financial architecture simply because her contribution is unpaid. Assets, savings, insurance, retirement planning, emergency access, and financial information should not automatically belong only to the earning spouse.
There is a temptation in financial-independence discussions to make money sound like the solution to every difficulty women face. That would be misleading. A woman can earn extremely well and still experience family pressure, unsafe relationships, workplace discrimination, loneliness, burnout, or limited control over her own time.
Financial independence is therefore a foundation rather than a complete definition of empowerment. It gives a woman more options, but those options still depend on education, health, legal awareness, social support, confidence, family circumstances, and the quality of the relationships around her.
The goal should also not become another impossible standard in which women are told they must earn, invest, care for everyone, build wealth, maintain a perfect family, and never need support. Independence does not mean refusing help. It means having enough agency that receiving help remains a choice rather than a condition for survival.
There is no single salary or investment number that makes a woman financially independent. A ₹50,000 emergency fund may be enormously meaningful to one person and inadequate for another because income, responsibilities, family structure, debt, location, and lifestyle differ.
A better way to measure progress is through practical control.
| Question | Dependence | Growing financial independence |
|---|---|---|
| Can she access money in an emergency? | Must ask someone else | Has accessible personal or jointly protected funds |
| Does she understand family finances? | Information sits mainly with another person | She knows assets, liabilities and major commitments |
| Can she support her parents reasonably? | Requires repeated permission | Contribution can be discussed as an equal household decision |
| Does she invest for herself? | Savings are mainly informal or controlled by others | She builds investments and retirement assets consciously |
| Can she survive a temporary income loss? | Immediate dependence begins | Emergency savings provide breathing room |
| Does she participate in major financial decisions? | Decisions are mostly communicated to her | Decisions are made with her |
| Does she have personal financial goals? | Family goals consume the entire plan | Family and individual goals coexist |
The objective is not financial isolation from the family. The objective is financial participation inside it.
For many women, the dream of earning their own money has very little to do with becoming richer than somebody else. It is about experiencing the quiet dignity of knowing that a medical bill, a gift for her parents, a course she wants to study, a small personal purchase, or an unexpected crisis will not immediately place her in a position of dependence. Financial independence does not make relationships unnecessary; it allows a woman to enter those relationships with greater confidence, contribute from a position of strength, and preserve a part of herself that does not disappear when her marital or family role changes.
Financial independence for women should not be viewed as reducing the importance of husbands, fathers, or families. A financially capable partner can strengthen the household because responsibility, risk, planning, and long-term security no longer sit entirely with one person. Men also benefit from relationships in which money can be discussed transparently and both partners understand investments, insurance, debt, emergencies, and retirement, because equality removes the pressure of treating one person as the permanent provider and the other as the permanent dependent.
The most important financial milestone in a woman’s life may not be the day she becomes wealthy. It may be the much earlier day when she realises that an unexpected expense will not frighten her, that she can support her parents when they need her, that she understands where her money is invested, and that an important life decision does not depend entirely on somebody else’s permission or bank balance.
India’s progress in women’s financial inclusion is real. Women hold a majority share among Jan-Dhan account holders, their SIP assets have grown strongly, and younger women are beginning their investment journeys earlier. At the same time, women remain underrepresented among mutual-fund investors, and having a bank account or earning a salary still does not automatically translate into full financial control.
That is why the conversation should move beyond asking why women want to make money. A more useful question is what money allows them to protect: their choices, their parents, their future, their dignity, and their ability to stand on their own feet when life does not go according to plan.
For many women, becoming rich can wait. Becoming financially independent cannot.
Financial independence gives women greater control over everyday choices, emergencies, long-term planning, and major life decisions. It does not mean avoiding family support; it means having enough financial agency to participate in life as an equal adult rather than depending entirely on someone else for every important need.
No. Wealth usually refers to having substantial assets or high net worth, while financial independence is more about control, access, security, and the ability to support yourself when necessary. A woman can be financially independent without being rich if she has savings, financial awareness, and the ability to make reasonable decisions about her own money.
For many women, earning their own money supports personal dignity, career identity, emergency security, and the ability to contribute to both their marital family and their parents. It can also reduce the emotional pressure of having to justify every personal expense or depend entirely on a spouse for financial access.
Many women want the freedom to help their parents with healthcare, emergencies, gifts, or everyday needs without feeling that they must first seek permission. As daughters increasingly share responsibility for ageing parents, personal income and savings can make that contribution easier and more dignified.
A homemaker may not have a salary, but she can still have meaningful financial agency if she has access to money, savings in her name, insurance, retirement planning, knowledge of family finances, and a genuine role in financial decision-making. Financial independence should not be measured only by monthly income.
Personal savings can provide security during career breaks, illness, job loss, relocation, emergencies, or periods when household income is under pressure. Having a personal financial cushion does not imply mistrust; it is a normal part of responsible financial planning.
Financial independence can make relationships more balanced because both partners can participate in decisions from a position of greater security. It can reduce the risk of one person remaining in an unhealthy situation solely because leaving would create immediate financial hardship.
Earning money means receiving income, while financial control means understanding, accessing, saving, investing, and making informed decisions about that money. A woman can earn a salary but still lack financial independence if she has little say over how money is managed.
A practical starting point is to maintain an active bank account, create an emergency fund, understand household finances, build personal savings, learn the basics of investing, and participate in insurance and retirement planning. The goal is not to master everything immediately but to gradually build financial knowledge and control.
No. Healthy families depend on one another emotionally, practically, and sometimes financially. Financial independence does not mean refusing support; it means having enough agency that support remains a choice rather than a necessity for basic survival or everyday decision-making.
Annapurna is an H View contributor covering relationships, family, lifestyle, entrepreneurship, and everyday decision-making. Her articles focus on emotional clarity, practical understanding, and human-centered perspectives that help readers think better about personal and professional situations.
Share your real experience and help other readers decide better.
No community views yet. Be the first to share yours.
Open LinkedIn for a few minutes and you will probably come across a colourful graphic…
Harika October 6, 2026 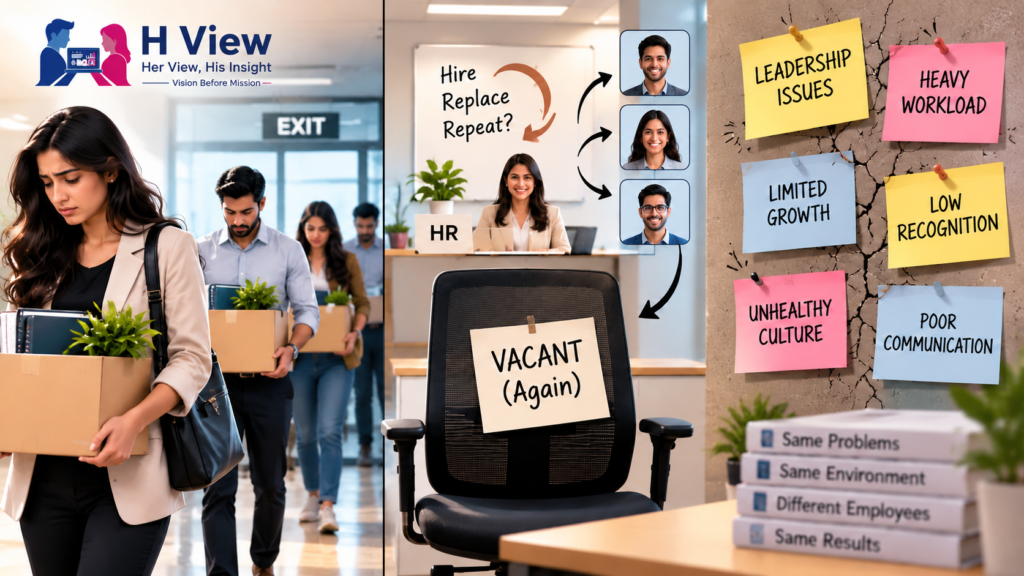
When an employee resigns, many organisations move quickly into replacement mode. The manager informs HR,…
Harika October 6, 2026 
For many corporate employees, the workday begins long before they actually start working. They wake…
Harika October 5, 2026 
Many projects begin with an assumption that sounds reasonable on paper: the client will explain…
Harika October 1, 2026